Jyothy Labs
A ₹5,000 loan from his brother, a year of failed kitchen experiments and one bottle of purple liquid. The story of how M.P. Ramachandran's Ujala built Jyothy Labs, and what the end of the Pril licence means for it.
PUBLISHED 30 SEPT 2026
- Ticker
- JYOTHYLAB
- Exchange
- NSE
- Sector
- FMCG
- Market Cap
- ₹6,853 Cr
THE ₹5,000 FROM HIS BROTHER
The Borrowed Money Behind a Purple Bottle
In 1983, in Thrissur, Kerala, a man named M.P. Ramachandran borrowed ₹5,000 from his brother. It was not a fortune even then, and it was not meant to fund an empire. It was meant to fund a temporary factory on a piece of family land, and a single idea about how to make white clothes look whiter.
The idea came from irritation. Ramachandran was dissatisfied with the fabric whiteners available at the time, and he had read about purple dyes in a chemical industry journal. That was the head start the record shows: a grievance, a magazine article and money from a relative. Nothing in the accounts of the period mentions a research team, an investor or a distribution network waiting to stock whatever he made.
He named the company Jyothy Laboratories, after his daughter Jyothy. The name is worth pausing on, because it tells you what kind of business this was. It was a family project, carried out at family scale, and it would stay closely tied to the family for the next four decades. His daughter, M.R. Jyothy, became Managing Director on 1 April 2020 and now serves as Chairperson and Managing Director, while he holds the title of Chairman Emeritus.
Most stories about Indian consumer companies begin with a giant: a multinational, a conglomerate, a famous name with a factory network. This one begins with one bottle of purple liquid and a borrowed sum of ₹5,000. Everything that follows, from dishwash bars to mosquito repellents to a 2026 licensing dispute with a German multinational, traces back to that bottle. It is also why the rest of this story keeps returning to it.
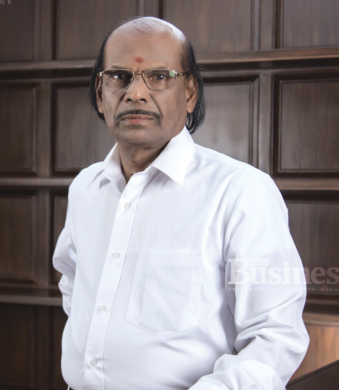
Born in Kandanassery, Thrissur, Ramachandran completed a B.Com at St. Thomas College, Thrissur, and studied financial management in Mumbai. He founded Jyothy Labs in 1983 with ₹5,000 borrowed from his brother and built it around one product, Ujala Supreme.
FY25 sales of ₹2,844 crore are roughly 5.7 million times the ₹5,000 that started it all.
A YEAR IN THE KITCHEN
When Nothing Worked for Twelve Months
Having a good idea and having a working product are very different things. Ramachandran spent about a year experimenting with formulations in his kitchen, boiling, diluting and testing whiteners. One account of the period describes all of it as "in vain" until the purple dye approach finally held up.
For a year, nothing worked. That sentence is the real low point of the story, more than any boardroom crisis that came later. A man with borrowed money, a family to support and no laboratory kept going back to the same kitchen and the same failing experiments. Nothing in the record says what kept him going, and it would be dishonest to invent a motive. What the record does show is that he stayed at it long enough to find the formula.
The product that emerged was a liquid fabric whitener, eventually sold as Ujala Supreme. The company's own history describes it as creating a category: liquid fabric whiteners, meant to give brighter, whiter clothes for work and school. The word "category" matters. Ujala was not a slightly better version of something families already bought in the same form. It was the thing that made people start asking for the product type at all.
It helps to sit with the scale of that first year. A formula that took twelve months to get right, produced in a temporary factory on family land, sold for ₹40,000 in its first year of trading. Nobody looking at those figures in 1984 could have read an eventual national brand in them. What they showed was a product that worked and a founder who had no intention of quitting, which is the only signal early numbers usually give.
Results in the first year were modest. According to Ramachandran's Wikipedia biography, first-year sales totalled ₹40,000. That is a long way from the ₹2,844 crore the business recorded in FY25, and a reminder that the compounding happened slowly, over decades, rather than in a single breakout season.
SIX WOMEN, HOUSE TO HOUSE
One Bottle at a Time
A new product with no advertising budget has exactly one way to find customers: someone has to carry it to them. According to a Zee News profile, a group of six women initially sold Ujala house to house. The work was done by hand, one household at a time, with the doorstep as the shop.
That method has a hidden advantage. A product sold face to face does not need a brand campaign to introduce it; the person at the door is the introduction. The same profile says Ujala gained popularity across South India first, before expanding nationwide.
The company's own timeline marks the steps. In 1992, it established a factory in Chennai to manufacture Ujala, a sign that demand had outgrown the original Thrissur arrangement. In 1997, Ujala Supreme was launched in all states of India. Fourteen years after a ₹5,000 loan, the purple bottle had a national footprint.
Then the company did what single-product businesses rarely manage: it used the first product's cash to try a second and third. In 2000, Maxo was launched in West Bengal and Exo was launched across South India. In 2007, Jyothy Labs listed on the BSE and NSE. In 2011, it acquired a controlling stake in Henkel India Limited, which according to Finshots meant taking a 50.97% stake for ₹118.7 crore.
The Jyothy Journey — From ₹5,000 to a National House of Brands
THE 84.1% QUARTER
A Moat Shaped Like a Bottle
The clearest measure of how completely Ujala owned its category comes from a broker's research note. It reports that Ujala Supreme's market share in fabric whiteners rose from 83.6% in the fourth quarter of FY21 to 84.1% in the fourth quarter of FY22. That is a figure from 2022, and it should be read as a dated snapshot rather than today's number. Still, a product holding more than four-fifths of its category is an unusual thing to be able to say.
Why does a share like that last? Part of the answer is that a category created by one company tends to be defined by that company's product. When families think of a liquid whitener, they think of the purple bottle that started it. Part of it is distribution: Finshots reports that Jyothy reaches about 4 million outlets nationwide, a network that took decades to assemble and cannot be rebuilt in a season.
The third part is economic. A dominant product in a niche category generates steady cash without needing a huge advertising push, and that cash can fund the brands that are still fighting for share. In Jyothy's case, it funded Exo, Maxo and the broader portfolio. Finshots reports that six power brands now account for 82% of total revenues. The company's latest investor material still says Ujala Supreme has maintained its four-decade leadership in fabric whiteners.
The company also invested in keeping the bottle visible. Its timeline records that Ujala Crisp & Shine was launched across India in 2008, that the registered office moved that year to a new building called Ujala House in Kondivita, Andheri East, and that in 2010 Sachin Tendulkar was signed as brand ambassador for Ujala Supreme. A company that names its headquarters after its first product is telling you where it thinks its identity lives.
A moat is not the same as a guarantee, and the last section of this story shows why. But the purple bottle did what moats do: it bought the company time, cash and room to make mistakes.
₹2,844 CRORE ON THE LEDGER
Forty Years of Compounding
Screener's data shows sales of ₹1,885 crore in FY21, rising to ₹2,844 crore in FY25. That is about 11% compounded annually over four years, with growth slowing to 3.3% in FY25. Net profit over the same period was more uneven: ₹190 crore in FY21, dipping to ₹139 crore in FY22, then recovering to ₹370 crore in FY24 and ₹371 crore in FY25.
Sales (₹ Crore)
FY21 to FY25, as reported on Screener
~11% sales CAGR (FY21-FY25), slowing to 3.3% in FY25The dip in FY22 deserves a line of its own. Sales grew that year, from ₹1,885 crore to ₹2,193 crore, yet net profit fell from ₹190 crore to ₹139 crore. Screener's table does not say why, and this story will not guess. It does show that a business can keep growing its top line while its bottom line wobbles, and that Jyothy recovered to ₹240 crore in FY23 and ₹370 crore in FY24.
Two things stand out in these numbers. First, the company has a sizeable cash buffer: Finshots reports a cash balance of ₹997 crore and a nearly debt-free balance sheet. That cushion does not remove operating or competitive risk. Second, growth has slowed, and FY26 revenue of about ₹2,944 crore, reported in the company's May 2026 investor presentation, suggests that the expansion of recent years is now a steadier climb than a sprint.
Market value has moved the other way. Screener shows a market capitalisation of about ₹6,853 crore on 30 September 2026, with the shares at ₹187. When news of the Pril licence broke, Finshots noted the shares had already fallen 55% from their all-time peak. The business was not shrinking in that period, which tells you how much of a share price is expectation rather than earnings.
31 MAY 2026
The Day Pril Walked Out
In 2011, Jyothy took control of Henkel India, and with it a licence to market Henkel's Pril and Fa brands in India. That arrangement ran for about fifteen years. On 31 May 2026, it ended: Henkel AG decided not to renew the Pril and Fa licences beyond that date, and the brands were never Jyothy's to keep. Finshots notes that Henkel retained global ownership throughout.
The stakes were real. In its 9 May 2026 release, Jyothy described Pril as its anchor brand in dishwash liquids and Exo as the leader of its bars portfolio. It said Exo would be expanded across both formats after the licence expiry. These are different segments: their market-share percentages cannot simply be added. Analysts quoted by Finshots estimated that losing Pril and Fa could trim FY27 revenue by 6-8% and EBITDA by 14-16%; these were estimates, not reported outcomes. In a 15 June disclosure, Jyothy said it would pursue legal remedies concerning its contractual exit and transition rights.
The quarter in which the licences expired already showed the pressure. Q1 FY27 covers April-June 2026 and includes Pril and Fa sales through 31 May; it is not a full quarter without them. The company's August 2026 presentation reports revenue from operations of ₹773 crore, up 3% from ₹751 crore. Profit after tax fell to ₹47.6 crore from ₹96.8 crore, and gross margin slid to 38.5% from 48%, with the presentation citing input-cost inflation. Home care revenue fell to ₹280 crore from ₹308 crore, while fabric care grew 14.1% to ₹399 crore and accounted for 52% of that quarter's revenue.
That last detail closes the loop. The fabric-care portfolio, which includes Ujala, is carrying more of the company's weight as a licensed brand leaves. The segment figure covers multiple brands and should not be read as Ujala's revenue alone. Management, meanwhile, is pushing Exo, which it owns, across bar and liquid formats, describing FY27 as a year to be "cautiously optimistic" about. Whether that works is not yet known, and nothing here is a forecast.
Jyothy Labs is a story about owning versus renting. The product Ramachandran made in his kitchen was entirely his, and forty years later it still leads its category and keeps funding everything else. The brands the company leased, however successful, could be reclaimed by their owner on a date written into a contract. Borrowed ₹5,000 and a year of failed experiments built something no licence agreement could take away, because the asset was the formula, the name and the habit it created in millions of homes. Owning a brand removes one contractual dependency; it does not remove competition, execution risk or the need to keep earning customers' loyalty. It all began with one bottle of purple liquid.
Financial figures are sourced from publicly available information and may not reflect the most recent reporting period. This is a story, not investment advice — please verify all data independently before making any financial decision.
Like this story? You can get the next one.
If they're your kind of thing, we'll deliver one a week. No pressure, unsubscribe anytime.
No spam, ever. Leave whenever you like.